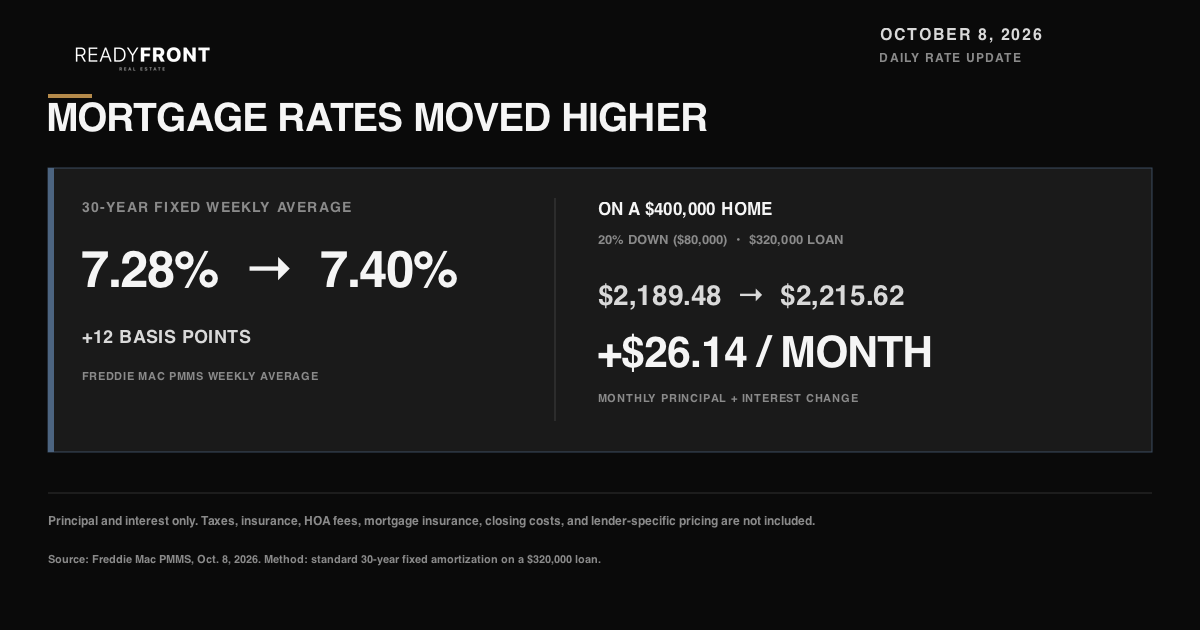
Mortgage Rates Moved from 7.28% to 7.40%: The Payment Impact on a $400,000 Home
On a $400,000 purchase with 20% down, a move from 7.28% to 7.40% changes the modeled principal-and-interest payment by $26.14 per month.
Freddie Mac's October 8 Primary Mortgage Market Survey reported that the national 30-year fixed weekly average moved to 7.40%, up from 7.28% the prior week. That is an increase of 12 basis points, or 0.12 percentage point.
What does that change do to a buyer's payment? Here is one clear example using the same loan amount, term, and payment formula at both rates.
The $400,000 Purchase Scenario
- Purchase price: $400,000
- Down payment: $80,000, or 20%
- Loan amount: $320,000
- Loan term: 30 years, or 360 monthly payments
At 7.28%, the monthly principal-and-interest payment is $2,189.48.
At 7.40%, the monthly principal-and-interest payment is $2,215.62.
The rate move changes the payment by $26.14 per month. Using the unrounded payment results, that is $313.63 over 12 months.
This is an illustrative calculation, not a lender quote. It includes principal and interest only. Property taxes, homeowners insurance, HOA fees, mortgage insurance, closing costs, discount points, and lender-specific pricing are not included.
What Austin Buyers Should Take from the Comparison
The headline is that the weekly average moved higher. The useful number is the dollar change: $26.14 per month in this example.
That number does not determine whether a particular home is affordable. Austin-area property taxes, insurance, HOA charges, maintenance, and the terms of an individual loan all affect the complete cost of ownership. Before making a decision, compare the full monthly payment for the specific property and loan offer you are considering.
An individual lender's rate may also differ from the national weekly average. Credit profile, loan type, down payment, discount points, fees, and rate-lock timing can change the terms offered to a borrower.
The Bottom Line
For a $400,000 purchase with 20% down, moving from 7.28% to 7.40% changes the modeled principal-and-interest payment from $2,189.48 to $2,215.62.
This comparison isolates the 12-basis-point move by holding the purchase price, down payment, loan amount, and term constant.
Use the rate movement as a prompt to update your numbers, not as a substitute for them. Ready Front Real Estate can help you evaluate the property-specific costs, and a licensed lender can provide the loan-specific quote and disclosures.
Frequently Asked Questions
What does a 12-basis-point increase mean?
One basis point is 0.01 percentage point. A move from 7.28% to 7.40% is an increase of 0.12 percentage point, or 12 basis points.
What is included in the $2,189.48 and $2,215.62 payments?
The figures include principal and interest on a $320,000, 30-year fixed-rate loan. They do not include property taxes, homeowners insurance, HOA fees, mortgage insurance, closing costs, discount points, or lender-specific pricing.
Is 20% down required?
No. The 20% down payment is a fixed assumption used to make the before-and-after comparison consistent. Available loan structures and their costs vary by borrower and lender.
Is 7.40% a guaranteed rate?
No. It is Freddie Mac's national weekly average for conventional, conforming purchase loans in the survey profile. An individual lender quote may be different and can change before a rate is locked.
Join the conversation
More from Ready Front Pulse
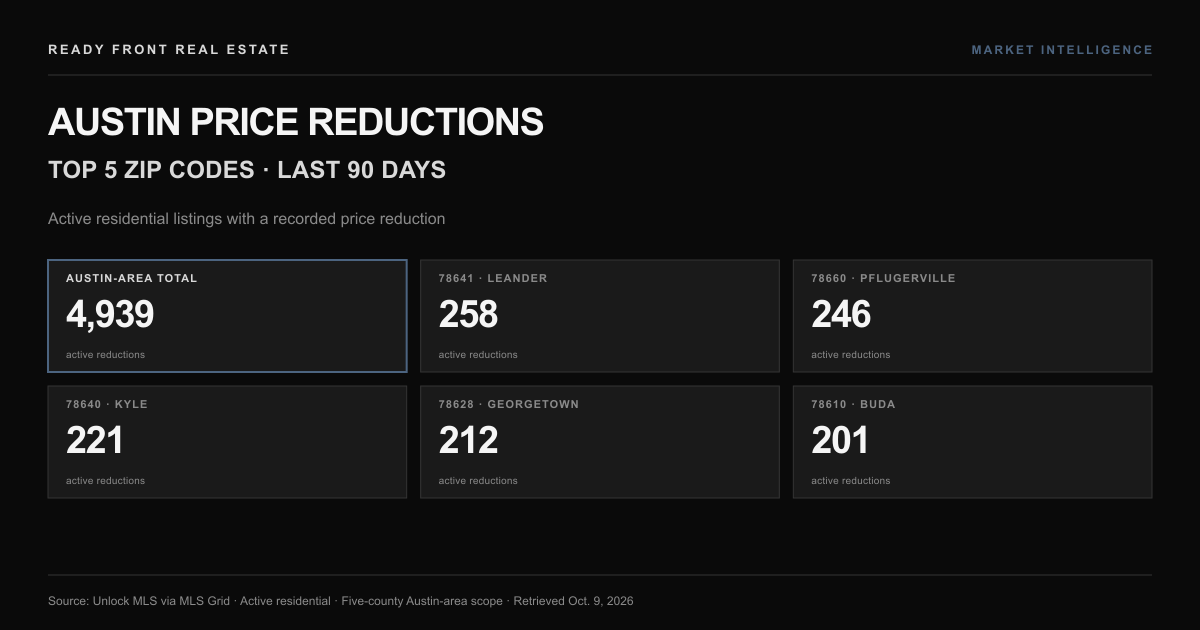
Where Active Price Reductions Are Showing Up Around Austin
A live Ready Front MLS snapshot of the Austin-area ZIP codes with the highest counts of active residential listings that reduced their asking price in the last 90 days.

ZIP 78641 September Market Update
95 September closings, a $463,000 median sold price, and the local context behind the numbers.

Bastrop September Market Update
Bastrop’s September supply story deserves a closer look.